
SIA opening balances: how to prepare and check your data



 2. November, 2026
Changing your accounting software or looking to take over the bookkeeping for your SIA? To continue working, the new system needs not only new invoices but also your company’s existing balances. In this guide, you will find out what to prepare, how to get started with pats.lv and how to check that the same amount has not been recorded twice.
Even a company with just a few transactions a month may have unpaid invoices, a loan or profits from previous years. If you transfer only the money in the bank, part of the company’s financial position will remain outside the new accounting records. A carefully prepared start, in turn, helps you use automation much more confidently in your daily work and understand where the figures in your reports come from.
What are opening balances in accounting?
Opening balances are the balances of your accounting accounts on the date from which you continue your bookkeeping in pats.lv. They show the company’s money, other assets, liabilities and equity. Changing software does not erase the company’s history: the new accounting records carry forward the position recorded in the previous system.
Customer debts, or accounts receivable, are amounts the company has yet to receive. Supplier debts are liabilities that still need to be paid. Both can exist at the same time, even if there is currently only a small balance in the bank account.
A newly established SIA and an existing SIA: how does getting started differ?
A newly established SIA has no accounting records from previous years of operation to transfer, so bookkeeping starts from scratch, with the very first transaction. This means there is no need to set a transition date or enter opening balances in pats.lv, because there simply are none yet. In Latvia, a reduced-capital SIA can be established with initial capital from EUR 1, making it easier than ever to start your own small business.
An SIA that has already been operating needs to transfer its previous accounting balances and their supporting information - the most precise document for this purpose is the general ledger. The latest annual report alone is not enough if the company has had new transactions since that date. You need data for the specific transition date you have chosen.
If you are still setting up your company, start with the guide to registering an SIA and starting your bookkeeping. In Latvia, registration takes place through the Latvian Register of Enterprises’ e-services portal. Here, we continue with the situation where you need to establish a clear and verifiable starting point in your accounting system.
1. Choose a single transition date
Decide up to which date the transactions have been finalised in the previous software and from the following day you will continue working in the new pats.lv system. Prepare all the data to be transferred as at the same cut-off date, meaning that all transactions up to the transition date must have been recorded.
Example: starting work from 1 July
The previous accounting records cover transactions up to 30 June. The opening balances reflect the position at the end of that day. From 1 July, new transactions are recorded in pats.lv. An old invoice that a customer pays in July remains linked to the transferred receivable.
Discuss any late-arriving documents in advance as well. If an invoice relates to the previous period, you need to agree on how it will be processed. Agree who will correct the old records and how any necessary changes will be reflected in the transferred data.
If, on the other hand, you start keeping your accounts in pats.lv on 1 January, the profit and loss accounts may have been closed, so the opening balances will differ. In either case - whether you switch at the beginning or in the middle of the year - pats.lv provides an accountant’s help so that the process runs smoothly and meets the requirements set out in law.
2. Prepare an account balance report and breakdowns of the amounts
Ask your previous accountant for an account balance report / general ledger, or prepare it using your old software. Add a breakdown showing which documents, customers, contracts and assets make up each significant amount.
Item | What to prepare | What to compare it with |
Bank and cash | The balance of each bank account and cash account separately. | Bank statements and cash records as at the transition date. |
Customer debts | The customer, invoice number, date and amount still unpaid. | Invoices, payments already received and credit notes. |
Supplier debts | Supplier documents and the remaining amounts payable. | Invoices and payments already made, including partial payments. |
Taxes and salaries | A breakdown of liabilities or overpayments and balances with employees. | Calculations, declarations and payments, and EDS information where necessary. |
Fixed assets | Acquisition cost, accumulated depreciation and carrying amount. | Fixed asset records and purchase documents. |
Inventory and advances | An inventory list and a breakdown of advances paid or received. | Stocktake data, contracts and documents. |
Equity and loans | Balances of share capital, results from previous years and loans. | Previous accounting records, decisions, contracts and repayments. |
This is a preparation checklist, not a list of every possible item. Your SIA may also have accruals, prepaid expenses or other amounts. If you do not know what an account represents, clarify its contents before entering it.
What should you write to your previous accountant?
“I plan to continue the bookkeeping for my SIA in the new pats.lv system from [date]. Please prepare an account balance report - the general ledger as at the transition date, lists of unpaid invoices (both customer and supplier invoices), a list of fixed assets and a record for each fixed asset, and breakdowns of the other significant amounts. If the transition takes place mid-year, I also need the reporting year’s income and expense data up to the transition date.” Salary calculations too, if there are employees.
3. Enter your opening balances in pats.lv
The pats.lv transition guide provides for entering your initial data in the “Opening balances” section of your profile, and the system is designed for self-employed people and SIA companies. Follow these steps:
Open the “Opening balances” section.
Indicate that you previously kept your accounts in another system.
Select the date from which you will continue your bookkeeping in pats.lv.
Enter the account balances from your previous system’s account balance report - the general ledger.
Check your entries and save.
The system automatically checks whether the balance sheet’s assets equal its liabilities and equity. Incorrect opening balances are not saved in the system and are not taken into account when preparing subsequent reports. This step is very important when you start working in pats.lv.
What can you do yourself, and where can an accountant help?
Section 35 of the Accounting Law allows an SIA’s sole board member, who is also its sole shareholder, to keep the company’s accounts themselves. Being a small company or having few transactions does not, in itself, replace this requirement. See Section 35 of the Accounting Law.
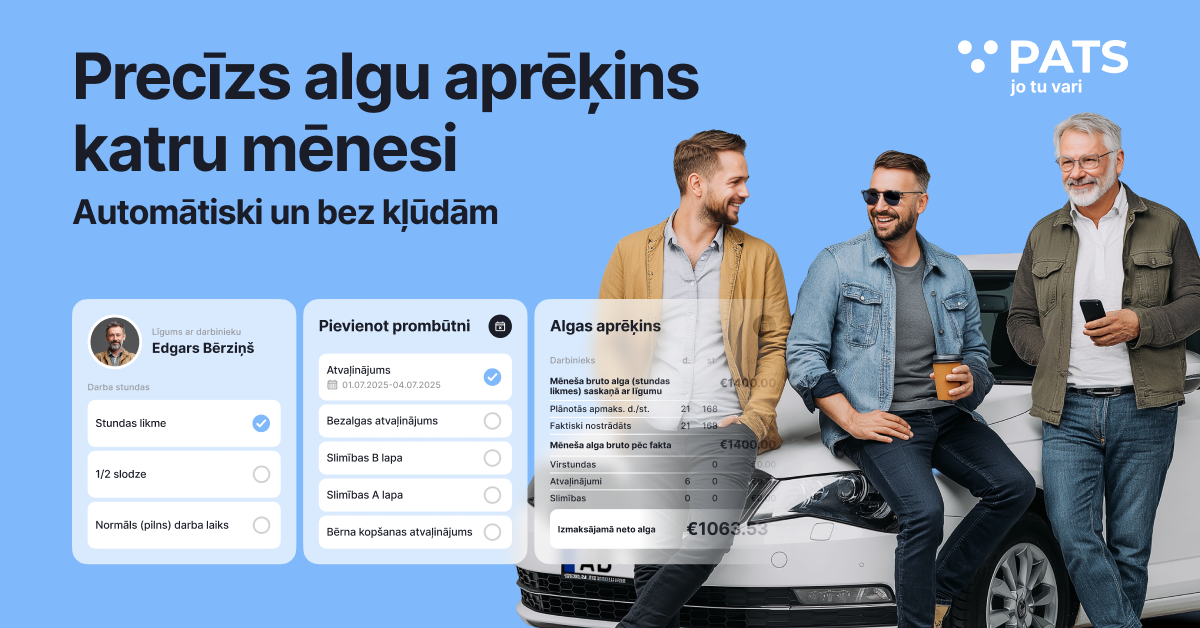
If you meet this requirement and choose to continue on your own, checking the opening balances can be a separate, clearly defined task for an accountant, and reminders are tailored to your profile. You gather the documents and explain your transactions; the specialist helps reconcile the accounts, the previous financial result and more complex items. When you switch to pats.lv, free accountant support for the first 30 days is available in the system, making the transition convenient, safe and accurate!
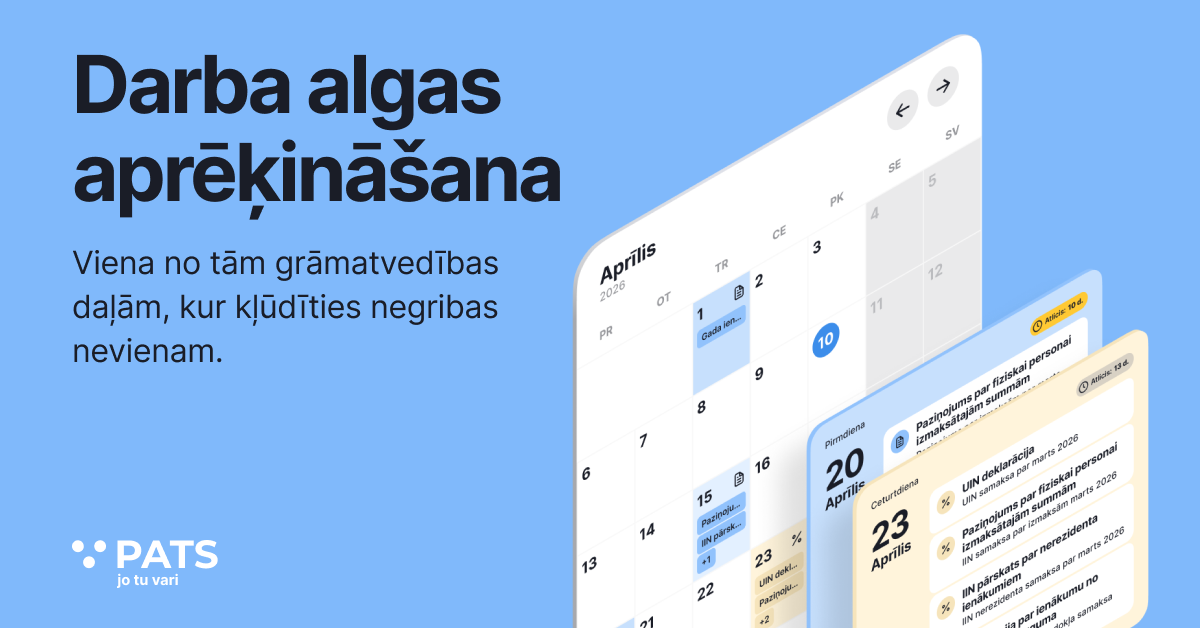
Another option is to work in pats.lv together with an accountant on an ongoing basis. The tax calendar is available to all system users. Agree who enters documents, who checks the books and who prepares and submits reports; issuing invoices is also possible without accounting knowledge. A clear division of responsibilities helps prevent the same document from being entered by both of you or by neither, and you can add a logo and design to your invoices.
Frequently asked questions about SIA opening balances
Can I get help during the transition?
Yes, switching to pats.lv or starting bookkeeping in general can seem like the hardest part, so we offer every new user starting work with their SIA in pats.lv an accountant’s help for the first 30 days completely free of charge.
Is it enough to transfer only the bank balance?
No, if the SIA also has other assets, debts or equity items. The bank is only one part of the company’s financial position. Transfer all applicable balances and their supporting information.
Does an annual report replace an account balance report?
An annual report can help you understand the company’s position at the end of the reporting year. However, transitioning on another date requires up-to-date data and a detailed breakdown. For example, the total amount owed by customers does not reveal which invoices are still unpaid.
Does a new SIA start bookkeeping with zero balances?
Most often, yes, but it also depends on what has already happened before you start keeping the accounts in the system. A share capital payment, a loan or another transaction must be taken into account. The company’s age alone does not determine its balances.
Do all old invoices need to be reissued when changing software?
No, changing software does not in itself constitute a new sale. Keep the original documents; automated invoicing also speeds up payment collection. Agree how to transfer the information about unpaid invoices, as this can save up to 80% of the time compared with manual data entry. Automatic receipt and invoice recognition reduces manual entry by up to 90%. Do not allow a transferred receivable or payable and a re-entered invoice to double-count the same amount, and the system’s automatic recognition reduces manual entry by up to 90%.
Do Lūrija or transaction checks replace the reconciliation of opening balances?
Opening balances require full supporting information from the previous accounting records. In some cases, registration in the State Revenue Service’s VAT register is necessary. Official registration requires a state fee, depending on the registration speed. The Register of Enterprises’ e-services are the cheapest way to register a company. Registration usually takes 1–3 working days. Checking an individual transaction is not proof that the entire transferred balance sheet is correct. Check any unclear balances against reports and documents, together with an accountant where necessary.

Get only what matters. Only what you need.