
SIA and the special VAT registration procedure: when it makes sense and how to use it



 25. September, 2026
Since 1 July 2025, a special VAT registration procedure for small businesses has been in effect in Latvia. Initially, it was used mostly by self-employed people, which we also covered in a blog article, but more and more legal entities - SIAs - are starting to use it too. If a company has a small turnover in Latvia but regularly buys services from abroad or goods from other EU member states, this procedure can significantly reduce its administrative workload. We have put together the key points that company managers and accountants need to know.
A reminder of what this special procedure is
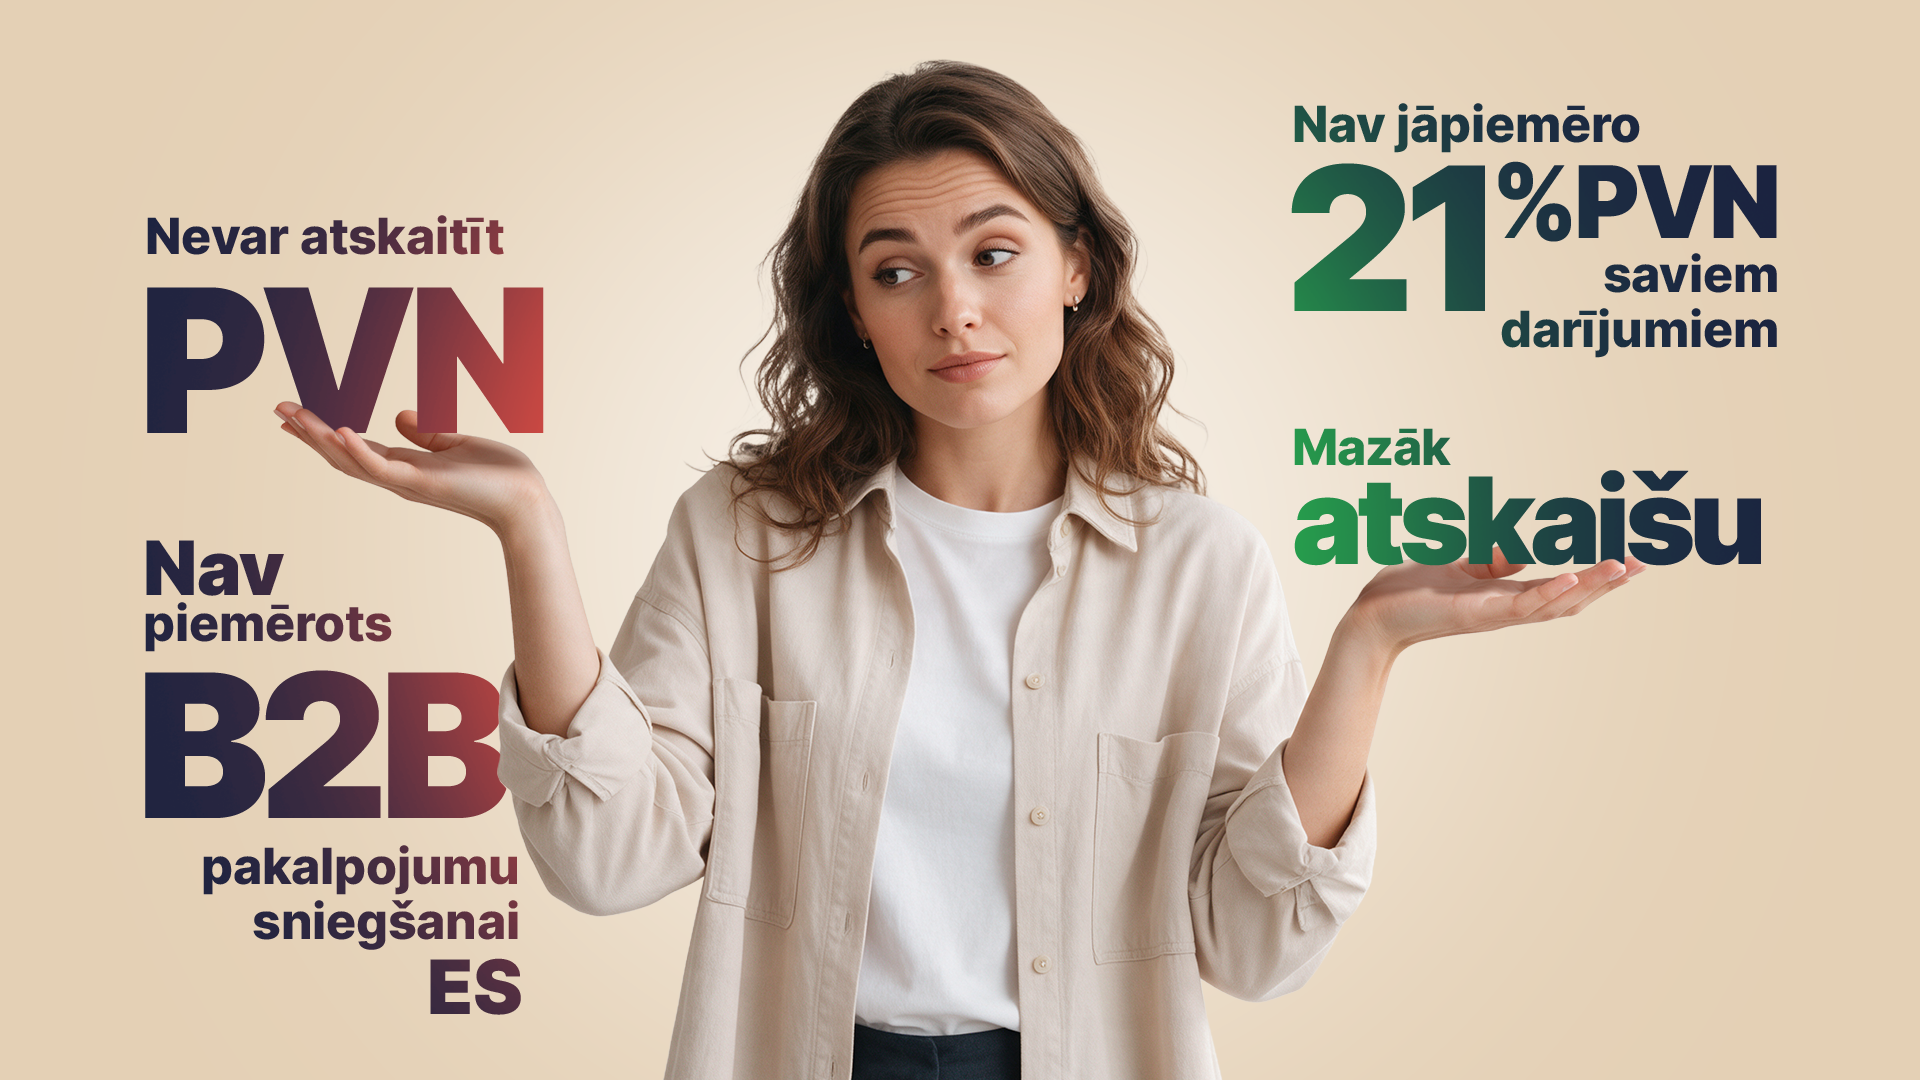
The special registration procedure is provided for in Section 139² of the Value Added Tax Law, which came into force on 1 July 2025 (VID). The idea is simple: the company is entered in the VID VAT register and receives a VAT number, but pays VAT only in specific cases - on services received and/or goods purchased. It does not have to pay VAT on its own revenue from selling goods or providing services.
In practice, this means that an SIA can deal with VAT obligations arising, for example, from buying advertising or software services from foreign platforms without moving to the full general VAT regime, with monthly VAT returns and VAT invoices for customers.
It is important to stress that registration under this procedure is voluntary. VID does not apply it automatically - the company must assess whether it meets the criteria and whether this option makes sense for it.
Who can use it
Two criteria must be met (VID):
- the total value of goods supplied and services provided, or turnover, in the territory of the Republic of Latvia did not exceed EUR 50,000 in the previous and current calendar years;
- the company does not provide services whose place of supply is determined under Section 19(1) of the VAT Law to registered taxable persons in other EU member states.
The first criterion is the same threshold that determines compulsory VAT registration under the general procedure. In practice, the second means this: if your SIA provides B2B services to EU companies - for example, IT development for a German client or consulting for an Estonian company - this procedure does not apply, and you must register under the general procedure.
Note that the turnover condition applies to both the previous and the current calendar year. In other words, a plan to stay below EUR 50,000 from now on is not enough - the threshold must not have been exceeded last year either.
Typical situations in which this is useful for an SIA
Most small companies encounter the special procedure through foreign digital services. Even a one-off purchase from a foreign service provider creates a VAT registration obligation, because in these transactions the recipient of the service in Latvia pays the tax. Common examples include:
- paid advertising on Facebook, Instagram or other foreign social media platforms;
- paid Google services - advertising, cloud storage and office tools;
- renting out property through Booking.com and similar platforms;
- selling goods through Shopify, Etsy, Amazon or other foreign platforms;
- subscriptions to AI tools such as ChatGPT for preparing content or finding information;
- Adobe and other foreign software for design, photo and video editing;
- foreign mobile apps and SaaS solutions for the company’s work;
- buying goods from suppliers in other EU member states - for example, equipment, raw materials or office technology from Lithuania or Poland.
If the company wants to treat these costs as business expenses, they must genuinely relate to the company’s activities, and each one must be supported by appropriate transaction documents - usually an electronic invoice in the case of digital services.
Benefits
VID lists several specific advantages for those who choose the special registration procedure (VID):
- there is no obligation to issue a VAT invoice for goods sold and/or services provided by the company - VAT is not charged on those goods and services;
- VAT is payable only on services whose place of supply is determined under Section 19(1) of the VAT Law, if received from taxable persons in the EU, third countries or third territories;
- VAT is payable only on acquisitions of goods within the EU;
- there is no need to submit a VAT return for the tax period;
- the calculated VAT must be paid to the state budget by submitting a notice of VAT payment.
For a company that works with individuals or Latvian customers and does not make large purchases subject to VAT, this offers two practical advantages: customer prices do not rise by 21%, and there is no cycle of monthly VAT returns in its accounting.
Limitations to consider
The other side of the coin is just as concrete:
- there is no right to deduct input VAT. This is the main factor in the decision. If an SIA makes major investments, buys goods for resale or regularly purchases services from Latvian VAT payers, the VAT paid remains part of its costs;
- the assigned VAT number may be used only to receive services covered by Section 19(1) from taxable persons in the EU, third countries or third territories and/or to acquire goods within the EU. It cannot be used for other transactions.
The second point is where small businesses most often make mistakes. The VAT number is not universal - it must not be shown on invoices to your customers or used to document transactions for which this procedure is not intended.
The decision is therefore usually a matter of calculation: how much annual input VAT would you lose the right to deduct, compared with the benefit of not charging customers 21% VAT and not maintaining full VAT records?
How to register
Registration takes place in the VID Electronic Declaration System (EDS). The company must submit the structured application “Iesniegums reģistrācijai PVN īpašajā reģistrācijas kārtībā (139.² pants) vai izslēgšanai no tās”.
Path in EDS: “Dokumenti” – “Izveidot jaunu dokumentu” – “Visi dokumenti” – “Iesniegums reģistrācijai PVN īpašajā reģistrācijas kārtībā (139.² pants) vai izslēgšanai no tās” – “Reģistrācija”.
VID decides whether to register the company or refuse its application within five working days of receiving it. A previously unregistered taxable person is considered registered under the special procedure on the second working day after the decision is posted in EDS (VID).
How to calculate and pay VAT
The calculation is simple:
(value of the service received or value of goods acquired in the EU × 21/100 = VAT amount in EUR
Deadlines to remember:
- the notice of VAT payment must be submitted by the 20th day of the month following the month in which the relevant service was received or goods were acquired within the EU;
- the tax must be paid to the state budget within 23 days after the month in which the transaction took place.
Submit the notice in EDS: “Dokumenti” – “Izveidot jaunu dokumentu” – “Pēc dokumentu grupas” – “Pievienotās vērtības nodokļa dokumenti” – “Paziņojums par PVN samaksu”. The procedure for completing the notice is laid down in Cabinet Regulation No. 17 of 3 January 2013, and a sample form is provided in Annex 5.
In months when no such transaction has taken place, no notice is required - unlike the general procedure, under which a return must be submitted for every tax period.
Moving from the general procedure
An SIA already registered under the general VAT procedure may change regimes if it meets the criteria. The application is submitted in EDS: “Dokumenti” – “Izveidot jaunu dokumentu” – “Nodokļu maksātāju reģistrācijas un datu izmaiņu” – “Iesniegums reģistrācijai PVN īpašajā reģistrācijas kārtībā (139.² pants) vai izslēgšanai no tās” – “Paziņojums saskaņā ar PVN likuma 73. panta 2.¹ daļu par pāreju uz PVN īpašo reģistrācijas kārtību” – “Maiņa, apstiprinot, ka ir tiesības pāriet uz īpašo PVN reģistrācijas kārtību”.
Moving to the special procedure brings two additional obligations that can have a significant financial impact on companies with assets on their balance sheet (VID):
- within 20 days of the registration date, a VAT return for the final tax period must be submitted, and the tax due must be paid to the budget within 23 days of the registration date;
- within 30 days of the registration date, a notice of VAT payment must be submitted in relation to the value of inventory and advance payments recorded in the accounts, the balance sheet value of fixed assets, and the costs of creating fixed assets and construction in progress for which VAT was deducted as input VAT. The tax must be paid within three working days of submitting the notice.
In practice, this means that input VAT previously deducted on inventory and fixed assets is, in part, “returned” to the budget. Moving regimes can prove costly for a company with a large warehouse stock or recently purchased fixed assets, so the calculation should be made before submitting the application.
Leaving the special procedure and returning to the general procedure
If a company wishes to move to the general procedure or becomes obliged to register under it (for example, it exceeds the EUR 50,000 threshold or starts providing services to EU taxable persons), it must submit an application in EDS under “Izslēgšana no PVN īpašās reģistrācijas kārtības (139.² pants)”, followed by an application for registration in the VID VAT register under the general procedure.
After leaving the special procedure, VAT for the period in which the person was removed must be calculated and paid to the state budget within 23 days of removal by submitting a notice of VAT payment.
If registration is late
If registration under the special procedure is late, but services have already been received from a taxable person in the EU, a third country or a third territory on which VAT is payable in Latvia, or goods have been acquired within the EU, a notice of VAT payment must be submitted and payment made for the period before registration. A separate notice must be submitted for each calendar month in which transactions took place.
That is why it is best to track when the company first buys a foreign digital service and register on time, instead of doing so after the fact.
Summary
The special VAT registration procedure makes sense for an SIA if its turnover in Latvia does not exceed EUR 50,000, its customers are mainly in Latvia or are individuals, it does not provide B2B services to EU taxable persons, and it uses foreign services or buys goods from the EU in its day-to-day work. It is less attractive if the company has a large amount of input VAT it wants to deduct or expects to grow quickly and exceed the threshold soon.
Are you an SIA owner who needs to become a VAT payer? Entrust your accounting to pats.lv - automatic tax calculation and preparation of reports and VAT returns.